Clark Mortgage

Email icon for Clark Mortgage enquiries

enquiries@clarkmortgage.co.uk

Specialists In: Complex Income, Adverse Credit, Portfolio Landlords, Development

Adverse Credit Mortgages With Chester’s Expert “Whole-of-Market” Mortgage Brokers

Enabling UK buyers with adverse credit to unlock the property finance they need

Securing a mortgage with a low or damaged credit score can feel impossible, especially when high-street banks rely on automated credit scoring that rejects you before anyone hears your story.

Clark Mortgages works differently. Based in Chester and Cheshire and supporting clients nationwide, we use whole-of-market access to connect you with specialist lenders who manually assess your situation and look at the bigger picture.

Straight-talking mortgage advice for buyers with adverse credit histories across the UK

Whether you’ve faced missed payments, a CCJ, an IVA, bankruptcy, or simply a thin credit file, we provide clear, jargon-free guidance and a fully managed process designed to reduce stress and maximise your chances of approval. With over 160 five-star reviews and a unique Application Guarantee that refunds your broker fee if we cannot secure a mortgage after a full application, you’re protected every step of the way.

Who We Help: Adverse Credit Solutions Built Around Real Life

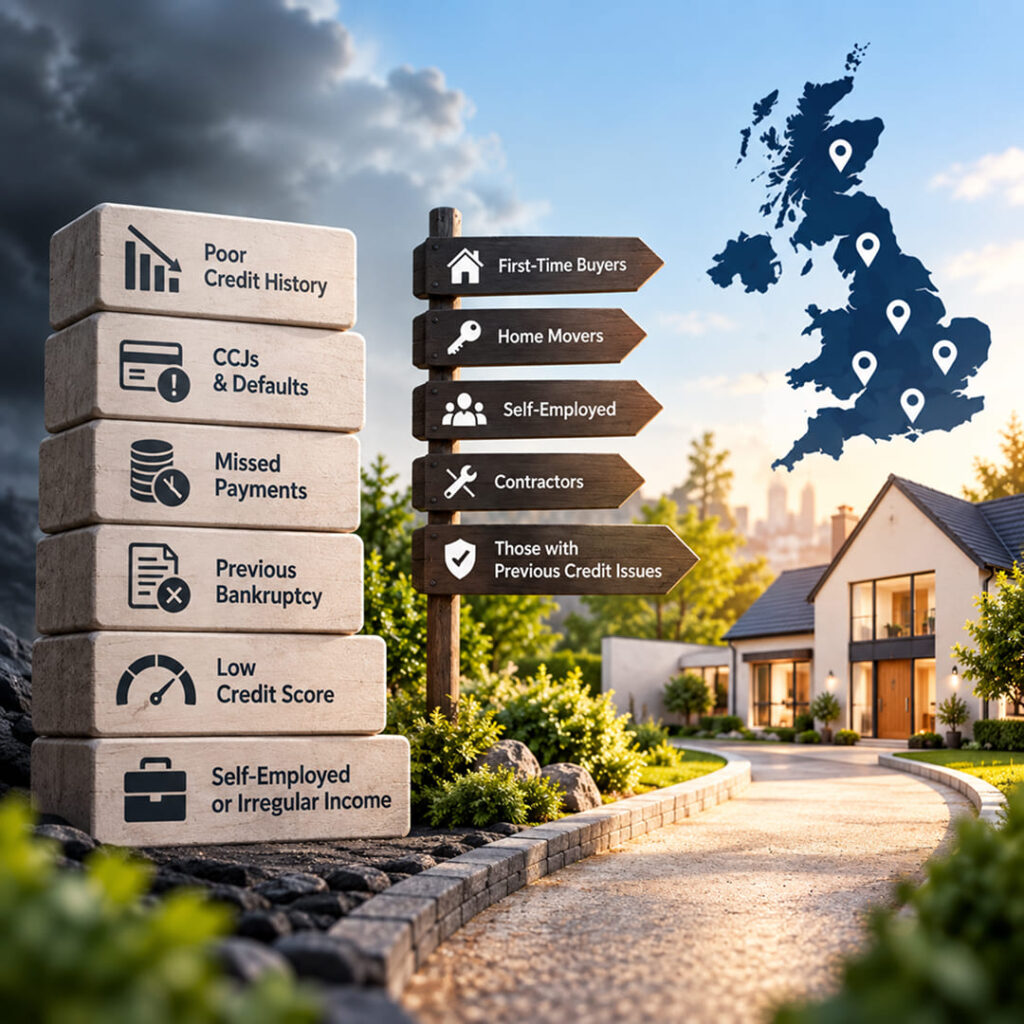
People come to us with all kinds of credit histories – and we build solutions around their real circumstances. We regularly help:

Your Adverse Credit Mortgage - Made Simple

Getting a mortgage with adverse credit doesn’t need to feel overwhelming. Our four-step process keeps everything clear, calm, and fully managed:

consultation icon

Assessment

We start with a free consultation to understand your goals, credit history, income, and deposit position. “Let’s understand your needs.

Group 1000008162

Market Search

We compare whole-of-market lenders, including specialist adverse credit lenders not available directly to the public, to find the right fit for your circumstances.

application-icon

Application

We handle the paperwork, prepare your case for manual underwriting, and manage communication with lenders to maximise approval chances. “The team manages the paperwork, ensures accuracy, and handles submission.

support-icon

Completion & Ongoing Support

We support you through completion and stay with you long-term, helping with future remortgages, refinancing, or credit-repair strategies.

Start Your Adverse Credit Mortgage Journey

Risk Warning: Your property may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it.

Adverse Credit & Complex Income Cases

Many lenders struggle when bad credit overlaps with non-standard income. We specialise in these multi-layered scenarios.

We help with:

Self-employed income with fluctuating profits

Contractors and freelancers with irregular earnings

Foreign income (including US-based income)

Gaps in employment or trading history

Multiple income sources or director-level remuneration

Cases previously rejected by other brokers or banks

Recently Discharged IVA, Bankruptcy & Debt Events

If you’ve come through a major debt event, you’re not alone – and it doesn’t mean homeownership is off the table.

We support:

Low Deposit Buyers with Adverse Credit

Even with a 5–10% deposit, specialist lenders may still consider your application – especially when supported by manual underwriting.

We help with:

Declined Applicants

If you’ve already been told “no,” we can often turn things around.

We support:

Why Adverse Credit Clients Choose Clark Mortgages

Frequently Asked Questions

Can I get a mortgage with a CCJ or default?

Yes – depending on when the CCJ/default occurred, whether it’s settled, and your overall financial profile. Many specialist lenders accept applicants with active or historic CCJs.

Most credit marks remain for six years, while bankruptcy can remain for up to ten years depending on the reporting agency.

Specialist lenders may accept deposits from 5–10%, though some cases require 15–25% depending on severity of credit issues.

Rates are typically higher due to perceived risk, but many clients later refinance onto cheaper mainstream deals once their credit improves.

Most specialist lenders require a hard check, though some offer soft-search options during initial assessment.

Yes – manual underwriting is ideal for self-employed applicants with irregular or complex income structures.

Speak to an Adverse Credit Mortgage Advisor Today

Clear, supportive guidance – even when banks say no.

Disclaimer – Your home may be repossessed if you do not keep up repayments on your mortgage. Think carefully before securing other debts against your home. Consolidating existing debts may increase the total amount payable.

Adviser helping client with mortgage application